The distinction between asset management vs private equity matters long before you are sitting across the table from an investor or a buyer’s due diligence team. Most founders and finance leaders understand the investment difference in broad terms. What they rarely think through is what that structural difference means for their accounting, their audit obligations, and the CPA relationship they need to build. By the time those questions become urgent, the preparation window has usually closed.
This is the gap that costs founders real money. Not because they chose the wrong fund structure, but because they chose the wrong financial infrastructure to support it. Whether you are a portfolio company that has taken on private equity capital, a fund manager building out financial oversight for the first time, or a growth-stage founder approaching a raise from institutional investors, the CPA relationship you have today was probably designed for a simpler version of your business. Understanding what your structure actually demands is the first step toward closing that gap through financial due diligence services and proper advisory support.
What You’ll Learn
• Why asset management and private equity create fundamentally different financial reporting and audit obligations, and what that means for the CPA relationship you build
• What a portfolio company needs to have in place financially before, during, and after a private equity investment or acquisition
• The specific accounting and advisory gaps that catch founders and finance leaders off guard when institutional capital enters the picture
• How to assess whether your current CPA is equipped for the level of scrutiny that PE investors, institutional buyers, and audit requirements will bring
• What financial due diligence, audit readiness, and outsourced controller support look like in a fund and investment context
What Actually Separates Asset Management From Private Equity (And Why It Changes Everything Financially)
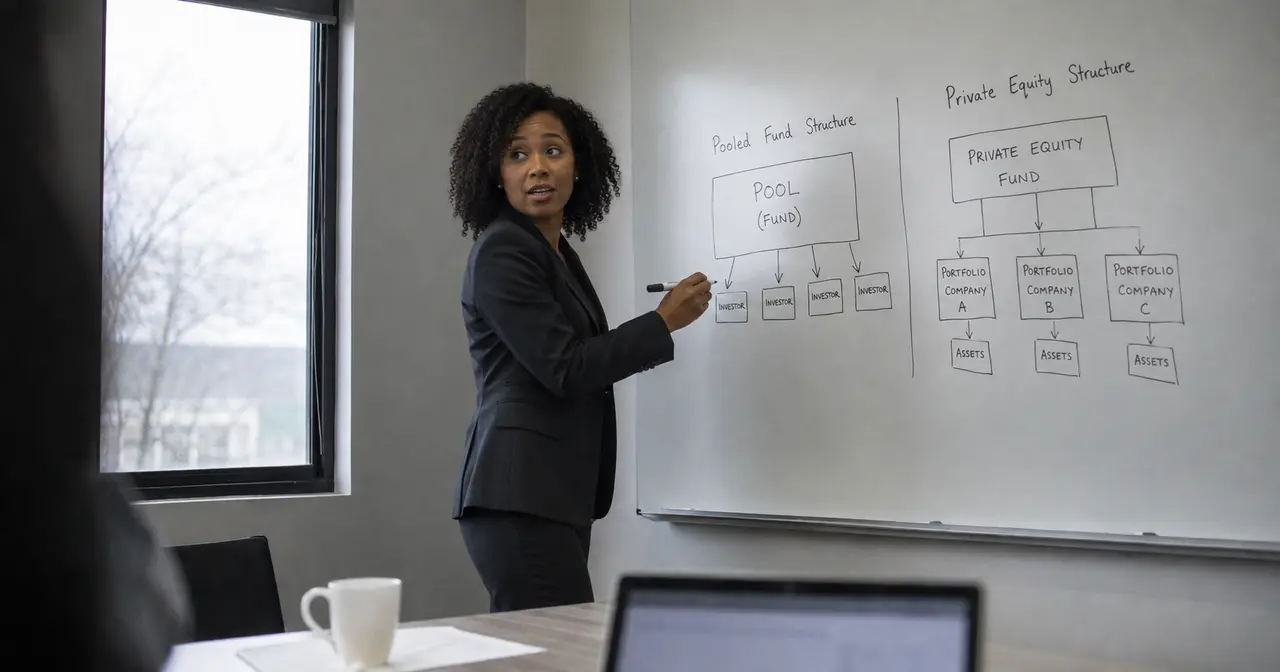
Asset management refers to the professional management of pooled capital across a portfolio of investments, typically on behalf of institutional or individual investors seeking returns over time. Private equity refers to funds that take direct ownership stakes, usually controlling or significant minority positions, in private companies with the goal of generating returns through operational improvement and eventual exit.
The investment strategy difference is real. The financial infrastructure difference is where most people get caught off guard.
Asset management firms are built around continuous portfolio oversight. Their accounting obligations center on:
• Net asset value (NAV) calculations and reporting to investors
• Performance attribution across fund positions
• Ongoing investor-level financial transparency
• Compliance with reporting standards specific to the fund structure
• Fee calculations and allocation accuracy across investor accounts
Private equity funds introduce a different layer of complexity entirely. Beyond the fund-level accounting, there is the question of what happens inside each portfolio company. A PE fund’s financial reporting is only as clean as the companies it holds. That creates a direct obligation for portfolio companies to maintain financial records that can withstand investor-level scrutiny at every reporting cycle, not just at exit.
Asset management and private equity are not just different investment strategies. They carry different audit obligations, reporting standards, and financial oversight requirements that have direct implications for the CPA relationship you need.
How Do Accounting and Audit Obligations Differ Between Asset Managers and Private Equity Funds?
This is the question most CPA conversations never reach. The high-level distinction between fund types is widely understood. The specific audit and reporting obligations attached to each structure are rarely walked through clearly before a problem surfaces.
Asset Management: What the CPA Relationship Looks Like
Financial oversight for asset managers centers on investor reporting accuracy and fund-level compliance. The accounting function needs to produce:
• Accurate NAV calculations on a regular reporting cycle
• Capital account statements that allocate performance correctly across investors
• Financial statements that meet the requirements of the fund’s limited partnership agreement or equivalent governance document
• Independent audit of fund-level financials, typically annually
The CPA working with an asset management firm needs specific experience in fund accounting advisory services. General business accounting does not transfer cleanly here. The allocations, the reporting standards, and the investor communication requirements are distinct enough that a firm learning on the engagement creates real risk.
Private Equity: A Materially More Complex Picture
For PE funds, the accounting obligation exists at two levels simultaneously: the fund itself and each portfolio company it holds.
At the fund level, obligations are similar to those of an asset management firm, with the addition of transaction accounting for acquisitions, disposals, and follow-on investments. At the portfolio company level, obligations typically include:
• Audited or reviewed financial statements, often required by the investment agreement
• Quarterly or annual reporting packages prepared to the PE firm’s specifications
• Earnings quality and revenue recognition documentation that can withstand scrutiny at the next capital event or exit process
• Outsourced controller or CFO-level oversight if the portfolio company does not have internal finance capacity at that level
The CPA relationship for a PE-backed company needs to cover audit for investment funds, ongoing financial advisory, and the kind of reporting infrastructure that holds up when the PE firm’s team or a future buyer starts asking hard questions.
| Dimension | Asset Management | Private Equity |
| Reporting obligation | NAV, capital accounts, fund-level statements | Fund-level plus portfolio company financial statements |
| Audit requirement | Annual fund audit standard | Fund audit plus portfolio company audit (often required by investment agreement) |
| CPA relationship type | Fund accounting and investor reporting specialist | Audit, assurance, outsourced controller, and transaction advisory |
| Primary scrutiny trigger | Investor reporting cycles | Capital events, board reporting, exit due diligence |
| Typical engagement triggers | Fund launch, reporting cycle, compliance review | Investment close, annual governance, pre-exit preparation |
What Does a Portfolio Company Need When a Private Equity Firm Is on the Cap Table?
This is where most founders get the timing wrong. The preparation a portfolio company needs before a PE firm enters the business is not the same as what they need after. And the gap between the two is where deals get complicated, valuations get negotiated down, and audit processes become disruptive rather than straightforward.
A portfolio company that has taken on private equity capital operates under a level of financial scrutiny that a tax-focused CPA relationship was never designed to handle.
When PE capital enters your business, the following obligations typically activate or intensify:
• Audited financial statements. Most PE investment agreements include an audit requirement. If your company has never been audited, the process of getting there from a standing start is significant and time-consuming.
• Quarterly reporting packages. PE investors expect structured financial reporting on a regular cadence, not the annual tax return your previous accountant produced in March.
• Earnings quality documentation. PE teams and their advisors will assess whether your revenue is real, recurring, and appropriately recognized. Revenue that looked fine for tax purposes may tell a different story under transaction-grade scrutiny.
• Cash flow reliability. The quality of your cash flow, how predictable it is, how tied it is to specific clients or contracts, will be examined closely at every capital event from the initial investment through to exit.
The audit and assurance function becomes the connective tissue between your day-to-day financial operations and the investor-facing reporting your PE partner expects to receive. Without it, you are flying without instruments in a situation where the instruments matter.
The founding team at a professional services firm preparing for a PE acquisition found out the hard way that their revenue recognition approach, which had been consistent for years, did not align with how the buyer’s team expected to see it presented. The result was not a failed deal, but it was a renegotiated valuation and a disrupted close process that added months to the timeline. The preparation work that should have happened 12 to 18 months before the LOI was being done under deal pressure instead. [CLIENT EXAMPLE: add a real client story about audit preparation before a PE transaction here]
The Business Due Diligence Playbook at LNB was built specifically for situations like this: a structured tool to help buyers and sellers manage every stage of the due diligence process, track progress, assign owners, and flag financial risks before they become negotiation leverage for the other side.
Why “We Have a Tax Accountant” Is Not Enough for Either Structure
This is the most common objection in the early conversation with any founder or finance leader who is approaching institutional capital for the first time. They have a CPA they trust. That CPA has handled their taxes for years. The relationship works. What is the problem?
The problem is that tax compliance accounting and investment-grade financial advisory are different disciplines. A CPA built around annual compliance is optimised to minimize your tax liability within the rules. A CPA working in the audit, assurance, and advisory space is optimised to give financial stakeholders, investors, buyers, and boards a credible, accurate picture of your financial position that holds up under external scrutiny.
Those two objectives are not in conflict. They are just different, and a practitioner built for one is not automatically equipped for the other.
Choosing a CPA based on familiarity rather than structural fit is one of the most common and most expensive decisions founders make when institutional capital enters their business.
For cpa for private equity firms, the distinction goes further. Audit experience, fund accounting knowledge, and transaction advisory capability are not add-on services. They are the core of what the engagement requires. A generalist firm taking on a PE-backed audit engagement without that experience base is not a risk worth taking when investor relationships and deal timelines are involved.
The client advisory services function fills the gap that pure compliance leaves open. Bookkeeping, financial reporting, outsourced controller support, and ongoing advisory create the financial infrastructure that investor-facing reporting is built on. For growth-stage companies approaching a raise or a PE transaction, CAS is often the first engagement that gets the books into a condition where an audit becomes possible without months of remediation work first.
How to Choose the Right CPA Relationship for Your Fund or Portfolio Company
The decision framework here is not complicated, but it does require honest assessment of where you are and where you are heading.
For Fund Managers
If you are running an asset management firm or a PE fund, the question is whether your current accounting infrastructure is built for fund-level reporting or for business accounting. They are not the same. Ask:
• Is your CPA experienced in fund accounting advisory services specifically?
• Can they produce investor-level reporting that meets your limited partnership agreement requirements?
• Do they have direct experience with the audit standards that apply to your fund structure?
• Have they worked with funds at your stage and scale before?
If the answer to any of those is no, the gap is real and it will surface at the worst possible time.
For Portfolio Companies
If your company has taken on PE capital, or is approaching a transaction where PE or institutional investors are involved, the framework is:
• Do you have audited financial statements, or can your current CPA get you there without a multi-month remediation process?
• Is your revenue recognized in a way that will hold up under a transaction-grade earnings quality review?
• Do you have quarterly reporting capability or only annual tax-based reporting?
• Is there an outsourced controller or CFO-level oversight in your financial function, or is your finance team operating below that capacity?
For cpa for alternative investments, the same principle applies. The CPA relationship needs to match the sophistication of the capital structure, not the size of the company alone. A $3M company that has taken on PE capital has more complex CPA requirements than a $10M company that has not.
For Founders Approaching a Raise
The Bay Area is one of the most active fundraising environments in the country. Growth-stage founders in San Francisco, Oakland, and the broader East Bay corridor regularly move from angel funding to institutional capital in compressed timeframes. The gap between a seed-stage financial infrastructure and what a Series A or B investor expects to see in your books is wider than most founders anticipate until they are in the middle of a diligence conversation.
Start the preparation work early. Twelve to 18 months before a formal process is not too soon. The founders who get to close cleanly are almost always the ones who treated financial readiness as an ongoing obligation rather than a pre-deal scramble.
Key Takeaways
• Asset management and private equity carry distinct audit, reporting, and CPA relationship requirements. The investment difference is understood. The financial infrastructure difference is where founders and finance leaders consistently get caught out.
• Portfolio companies that have taken on PE capital typically face audit requirements, quarterly reporting obligations, and earnings quality scrutiny that a tax-focused CPA relationship was never designed to handle.
• The outsourced controller and CAS function is often the first step toward building the financial infrastructure that makes an audit or investor review possible without disruption.
• Choosing a CPA based on familiarity rather than structural fit is one of the most consequential and most avoidable decisions a founder makes at this stage of growth.
• Preparation timelines matter. Twelve to 18 months before a formal capital event is the right window to start. Post-LOI is almost always too late to address structural gaps without affecting the deal.
Ready to Assess Whether Your Financial Setup Fits Your Structure?
If your company is approaching a raise, a PE transaction, or an investor review, the time to assess your financial infrastructure is before the process starts, not during it.
LNB Accounting CPAs works with growth-stage founders and finance leaders across the San Francisco Bay Area to close the gap between where their financial reporting is and where it needs to be for serious investor scrutiny. Our work spans audit and assurance, financial due diligence, and client advisory services, built for organisations that cannot afford surprises when institutional capital is involved.
Book a discovery call to talk through where you are and what your structure actually requires. No generic intake form. A direct conversation with someone who understands your situation.
Questions Founders and Finance Leaders Ask About Asset Management, Private Equity, and CPA Services
What is the difference between asset management and private equity from an accounting perspective?
Asset management firms focus on managing pooled capital across portfolios, which requires ongoing NAV reporting and investor-level financial transparency. Private equity funds take controlling or significant stakes in individual companies and require transaction accounting, portfolio company oversight, and performance reporting across the fund lifecycle. Each structure creates distinct obligations for the CPA and financial advisory relationships involved, and a generalist firm rarely has the depth to serve both well.
Does my company need an audit if it has taken on private equity investment?
In most cases, yes. PE investors typically require audited financial statements as part of their ongoing portfolio oversight and governance obligations. The scope and timing will depend on your investment agreement, but companies that have not prepared for an audit before a PE firm joins the cap table often face significant disruption when the requirement surfaces. Starting the audit readiness process before the investment closes is the cleaner path.
What does a CPA for private equity firms actually do differently?
A CPA working with private equity-backed companies goes well beyond tax compliance. They provide financial statement audits, earnings quality assessments, outsourced controller support, and ongoing advisory that aligns portfolio company reporting with what PE investors and future buyers expect to see. The engagement is structured around investor-facing financial credibility, not annual compliance.
How does fund accounting differ from regular business accounting?
Fund accounting involves tracking the performance of investments across a portfolio rather than a single operating business. It requires specific reporting standards, investor-level allocations, and often independent audit obligations that general business accounting does not. Firms operating in this space need a CPA with direct experience in fund accounting advisory services, not a generalist firm adapting general principles to an unfamiliar structure.
When should a company prepare for financial due diligence if a PE firm is considering an acquisition?
As early as possible, and ideally 12 to 18 months before a formal process begins. By the time a PE firm’s due diligence team arrives, your earnings quality, revenue recognition practices, and cash flow documentation need to be clean and presentable. Preparation that begins after an LOI is signed is almost always too late to address structural gaps without disrupting negotiations.
What is the difference between a CPA for alternative investments and a standard accounting firm?
A CPA specialising in alternative investments understands the specific reporting, compliance, and audit requirements of fund structures, including private equity, hedge funds, and venture capital vehicles. A standard accounting firm built around tax preparation and general compliance does not have the same depth in fund-level financial oversight, investor reporting, or transaction-specific advisory work. The difference matters most when the stakes are highest.
Start With a Conversation
The right CPA relationship does not happen by accident. It is a deliberate choice that reflects where your business or fund is headed, not just where it has been.
LNB Accounting CPAs is a specialist firm. We do not try to serve every accounting need. We focus on audit and assurance, financial due diligence, and client advisory services for organisations that are operating in, or moving toward, environments where financial scrutiny is real and the cost of being unprepared is measurable.
If you are in that situation, or approaching it, we would like to hear from you.