Most growth-stage founders encounter private equity loans the same way: someone across the table uses a term they have heard before but never had to map precisely, and the conversation moves faster than their ability to catch up. By the time the details matter, the deal is already in motion.
Understanding what you owe in a PE-linked transaction is not optional preparation. It is the difference between walking into due diligence with a clear financial narrative and spending the final weeks before close trying to explain inconsistencies you did not know existed. This post covers how PE debt structures actually work for founders, what obligations they create, and what you need to have sorted before a buyer’s team starts asking the questions that determine your valuation.
What You’ll Learn
• Why private equity loans create specific obligations for founders that are separate from the equity they give up, and what those obligations look like in practice
• How PE debt structures including leveraged buyout debt, venture debt, and seller notes sit in the capital stack and affect your cash flow and equity upside
• What a buyer’s due diligence team looks for when reviewing existing debt on your balance sheet, and what they flag as a risk
• The difference between growth stage debt and equity financing, and which carries more operational risk for a founder if revenue targets are missed
• What founders need to have documented and ready before a PE-linked deal enters serious due diligence
What Are Private Equity Loans, Really?
The term “private equity loan” gets used loosely, and that looseness costs founders clarity at exactly the wrong moment.
A private equity loan is not a single product. It is a category of debt financing that typically accompanies or enables a PE transaction, placed on the company being acquired or invested in rather than on the PE firm itself. The obligations it creates belong to the business, which means they affect cash flow, operating decisions, and ultimately the founder’s equity position.
The most common PE debt structures founders encounter include:
• Leveraged buyout (LBO) debt: Senior and subordinated debt used to finance an acquisition. The PE firm puts in equity; lenders provide the rest. That debt sits on the acquired company’s balance sheet from day one of the new ownership structure.
• Growth equity with debt components: Some growth equity deals include debt tranches alongside equity investment, creating fixed payment obligations even before the company has reached the scale to absorb them comfortably.
• Venture debt: A loan facility often used by VC-backed companies between equity rounds. It carries interest, warrants, and sometimes revenue-based repayment provisions. When a company carrying venture debt enters an acquisition process, that debt must be resolved at or before close.
• Seller notes: A portion of the sale price deferred and paid to the seller over time. The seller becomes a creditor of the business after close and takes on repayment risk if the business later struggles to meet its obligations.
Each of these structures creates a different set of obligations. Understanding which one applies to your situation is the first step toward understanding what you actually owe.
Our financial due diligence services are built specifically to help founders map these obligations before a deal gets serious, not after the term sheet is on the table.
How Do PE Debt Structures Affect What You Owe as a Founder?
This is where most founders have a gap in their understanding. They think about PE involvement primarily in terms of equity dilution: how much of the company they are giving up. The debt side of the equation gets less attention, and that is where surprises tend to live.
Private equity loans are not just financing instruments: they are a set of founder-facing obligations that determine how much of the deal proceeds you actually keep.
Here is how PE debt structures for founders translate into real obligations:
Interest Coverage and Cash Sweep Provisions
LBO debt carries interest that must be serviced regardless of how the business performs. If the business hits a rough quarter, the debt payment does not pause. Some structures include cash sweep provisions, which require that excess cash flow be directed toward debt repayment before any distributions are made. For a founder who expected to maintain some operational flexibility post-deal, this changes the calculus significantly.
EBITDA Covenants
EBITDA covenants are contractual thresholds tied to PE debt. They set a minimum earnings level the business must maintain. If the company’s EBITDA falls below that threshold, the lender may have the right to restrict distributions, demand additional collateral, or in severe cases, accelerate the repayment schedule. These are not abstract clauses. They are active constraints on how you can run the business.
Capital Stack Position and Founder Equity
Debt sits above equity in the capital stack. In a leveraged deal, that means senior lenders and subordinated lenders are paid before any equity holders see a return. If the business is sold again or recapitalized, those obligations are settled first. A founder holding equity at the bottom of a heavily leveraged capital stack may find that the headline deal value does not translate cleanly into proceeds in their account.
The practical implication: the more debt above you in the stack, the more the business needs to grow in value before your equity position increases meaningfully.
What Does PE Debt Do to Your Financials Before a Deal Closes?
A buyer’s due diligence team reviews your balance sheet as closely as your revenue numbers, and existing debt is one of the first things they use to judge whether your business is worth what you think it is.
Here is what they look at and what creates problems:
| Debt Item | What Buyers Review | Common Red Flags |
| Loan agreements | Current balances, interest rates, maturity dates | Undisclosed debt, incomplete documentation |
| Covenant terms | Compliance history, any waivers granted | Prior covenant breaches, unamended violations |
| Venture debt facilities | Warrant coverage, repayment triggers | Outstanding warrants not reflected in cap table |
| Seller notes | Payment terms, subordination agreements | Unclear priority relative to acquisition debt |
| Leverage ratios | Debt-to-EBITDA relative to industry norms | Ratios that suggest the business cannot absorb additional debt |
A company with venture debt on its balance sheet that has not been cleanly documented, or where warrant coverage has not been properly reflected in the cap table, creates work for the buyer’s team. Work becomes risk. Risk becomes a lower offer or a renegotiated structure.
Private equity financing risks in this context are often not about the debt itself but about how it is presented. Founders who can walk a buyer through their debt obligations clearly, with full documentation, close faster and with fewer surprises. Founders who cannot tend to find those surprises surfacing in the final weeks of due diligence, when they have the least negotiating power.
Growth Stage Debt vs Equity: Which Carries More Risk for Founders?
The standard framing is that debt is cheaper than equity because it does not dilute ownership. That is true in isolation. It is less true when you factor in what debt requires of you operationally if the business hits a difficult period.
The growth stage debt vs equity comparison for founders comes down to this:
Equity dilutes your ownership percentage. Debt creates fixed obligations that exist regardless of performance.
Consider two scenarios:
Scenario A: A founder takes on growth equity at a 20% dilution. Revenue misses targets for two quarters. The investor is unhappy, but there is no fixed payment obligation. The business keeps operating.
Scenario B: A founder takes on venture debt with a $2M facility. Revenue misses targets for two quarters. The interest payment is still due. If covenants are tied to revenue or EBITDA thresholds, the lender may have additional rights. Operational flexibility shrinks exactly when it is most needed.
This does not make debt the wrong choice. For the right company at the right stage, debt preserves equity and can accelerate growth without giving up meaningful ownership. The risk is specific to scenarios where revenue is variable, growth is not linear, or the business is approaching a transaction where the debt will need to be resolved.
Founders heading into a PE-adjacent deal should ask these questions before deciding how to think about existing debt:
• What are the covenant terms and what triggers them?
• What happens to this facility at close: does it get paid out, assumed, or renegotiated?
• How does a buyer’s model treat this debt when calculating enterprise value and equity proceeds?
• Are there warrants or equity components attached that need to be reflected in the cap table?
These are not complicated questions. They are just the ones that tend not to get asked until someone else is asking them first.
What Founders Need to Have Sorted Before PE Due Diligence Gets Serious
Preparation is not complicated. It is specific.
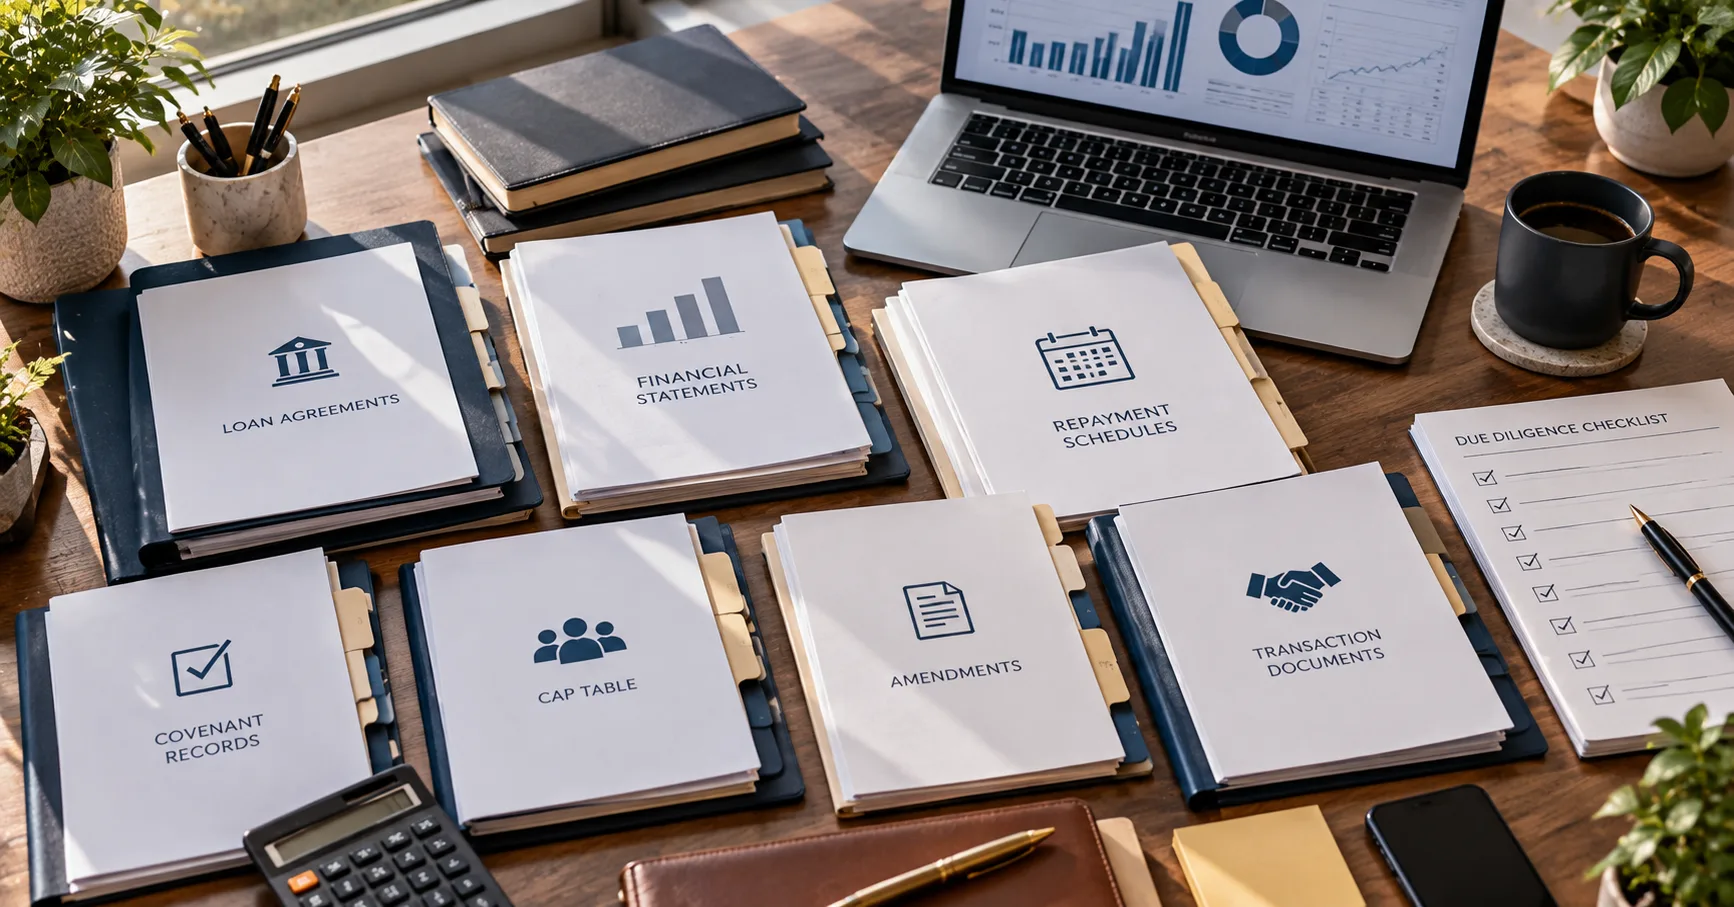
The founder debt obligations pre-acquisition that most commonly surface as problems in due diligence are not exotic. They are documentation gaps, covenant compliance questions, and balance sheet items that have never been presented for external review. Here is what to have ready:
Full debt documentation
• All loan agreements, including current balances, interest rates, and maturity dates
• Any amendments, waivers, or covenant modifications since the original facility was established
• Repayment schedules and any prepayment provisions relevant to a transaction
Covenant compliance history
• Written confirmation that all covenants are currently in compliance
• If there have been prior breaches, documentation of how they were resolved and any lender acknowledgment of cure
Cap table accuracy
• All warrants attached to debt facilities reflected accurately in the cap table
• Any convertible instruments that could affect the equity distribution at close
EBITDA documentation
• A clean, supportable EBITDA calculation, along with separate documentation of debt service obligations and any non-recurring adjustments.
• If your EBITDA has been calculated differently in different periods, be ready to explain why
A clear debt resolution plan
• Whether existing debt will be repaid at close, assumed by the acquirer, or renegotiated as part of the deal structure
• If seller notes are involved, documented terms and subordination agreements
The founders who get the best outcomes in PE-linked transactions are not necessarily the ones with the cleanest revenue numbers. They are the ones who walked in knowing exactly what they owed and to whom.
The Business Due Diligence Playbook gives founders a structured framework to track and manage every stage of this process across a 6 to 8 week transaction timeline. If you are heading into a deal, it is worth working through before the buyer’s team starts asking questions.
Questions Growth-Stage Founders Ask About PE Debt Before a Deal
What is a private equity loan and how is it different from a regular business loan?
A private equity loan is debt that typically funds or structures a PE deal, often placed on the acquired company rather than the PE firm. Unlike a standard business loan, it is tied to deal-specific covenants, interest coverage ratios, and repayment structures that create ongoing operational obligations for the business. The terms are driven by the transaction, not by the company’s standalone creditworthiness.
Do founders personally owe money when private equity takes on debt?
In most cases, founders are not personally liable for PE deal debt. However, the debt sits on the company’s balance sheet and directly affects cash flow, operating decisions, and equity distributions. If the business cannot service the debt, the consequences flow through to founder equity and, in some structures, to operational control.
What are EBITDA covenants and why do they matter in a PE deal?
EBITDA covenants are contractual requirements tied to PE debt that set minimum earnings thresholds the business must maintain. If the company’s EBITDA falls below those thresholds, the lender may have the right to restrict distributions, demand additional collateral, or accelerate repayment. This directly limits what a founder can do operationally, especially during a period of underperformance.
What is a seller note and how does it affect founders in an acquisition?
A seller note is a form of deferred payment where part of the sale price is paid to the seller over time rather than at close. It creates a creditor relationship between the former owner and the acquiring entity. The seller takes on repayment risk if the business later struggles to meet its obligations. The terms of the note, including subordination and payment priority, matter significantly to both parties.
How does existing venture debt affect an acquisition deal?
Venture debt on a company’s balance sheet is reviewed closely by any acquirer’s due diligence team. It can reduce the equity proceeds available to sellers, create repayment obligations that need to be addressed as part of the transaction, and complicate deal structuring if the terms are not well documented or if covenants have been breached. Warrants attached to the facility also need to be accurately reflected in the cap table.
What financial documents do founders need to prepare before a PE due diligence review?
Founders should have full documentation of all existing debt facilities: loan agreements, current balances, covenant terms, repayment schedules, and any waivers or amendments. Clean, auditable financial statements, a clear EBITDA calculation, and documentation of debt service obligations are all essential before serious deal conversations begin. The absence of any of these items creates friction in due diligence that founders rarely have time to resolve cleanly once the process has started.
Key Takeaways
• Private equity loans are not a single product. They include LBO debt, growth equity debt components, venture debt, and seller notes, each of which creates different obligations for the business and the founder.
• Debt sits above equity in the capital stack. The more leverage in a deal structure, the more the business must appreciate before your equity position increases meaningfully.
• EBITDA covenants, cash sweep provisions, and interest coverage requirements are active operational constraints, not background legal terms.
• A buyer’s due diligence team reviews existing debt with the same scrutiny as revenue. Undocumented debt, prior covenant breaches, and unresolved warrants are all flagged as risk.
• Growth stage debt vs equity is not a simple cost-of-capital comparison. Debt creates fixed obligations that compound pressure during a revenue miss, while equity only dilutes ownership percentage.
• The founders who close deals on their terms are the ones who knew their debt obligations completely before due diligence started, not the ones who discovered gaps under buyer scrutiny.
Ready to Go Into a Deal Without the Surprises?
If your company is approaching a transaction, we can help you get your debt obligations documented and deal-ready. At LNB Accounting, we work with growth-stage founders across the San Francisco Bay Area, and our financial due diligence services are built for founders who need to know where they stand before the other side of the table does. Contact us to talk through where your business stands.
The Business Due Diligence Playbook is a practical starting point: a structured tool that helps you manage every stage of the process across a 6 to 8 week transaction timeline, so nothing gets missed when it matters most.hing the single audit threshold for the first time, a direct conversation with our team is the right starting point. We work with nonprofit organizations through the full audit process, from preparation through to final report. Contact us to talk through your situation.